
Planning for retirement can feel like trying to assemble complex furniture without the manual. You work hard for decades, saving money in special accounts like traditional IRAs or 401(k)s. Then, a specific milestone arrives where the government expects you to start taking money out each year. This requirement often catches people off guard. Understanding how much you need to withdraw, when to take it, and how to stay completely compliant with tax rules does not have to be scary or stressful.
Using an rmd calculator takes all the confusion out of the planning process. Instead of guessing complex math formulas or stressing over IRS distribution tables, you simply enter a few basic numbers and get an immediate, accurate answer. Having a reliable tool helps you schedule your yearly budget, avoid massive tax penalties, and enjoy your golden years with complete peace of mind. Let us break down everything you need to know about calculating your distributions in plain, clear language that anyone can follow.
What Is an RMD and Why Does It Matter for Your Money?
RMD stands for Required Minimum Distribution. It is the minimum amount of money that the tax authorities require you to withdraw from certain tax-deferred retirement accounts every single year once you reach a specific age. When you saved money during your working years in traditional IRAs or 401(k) plans, you received nice tax breaks. The government allowed your savings to grow without taxing them right away. However, those tax breaks do not last forever, and eventually, taxes must be paid on those savings.
The main reason this formula matters is that failing to withdraw your mandatory amount leads to expensive penalties. In the past, missing a payment meant paying a huge fifty percent penalty on the amount you failed to take out. Even though recent rule changes reduced this penalty to twenty-five percent, or ten percent if corrected quickly, it is still money you should never lose. Keeping track of your annual requirements ensures you keep every dollar possible inside your own family pocketbook.
How Does an RMD Calculator Work?
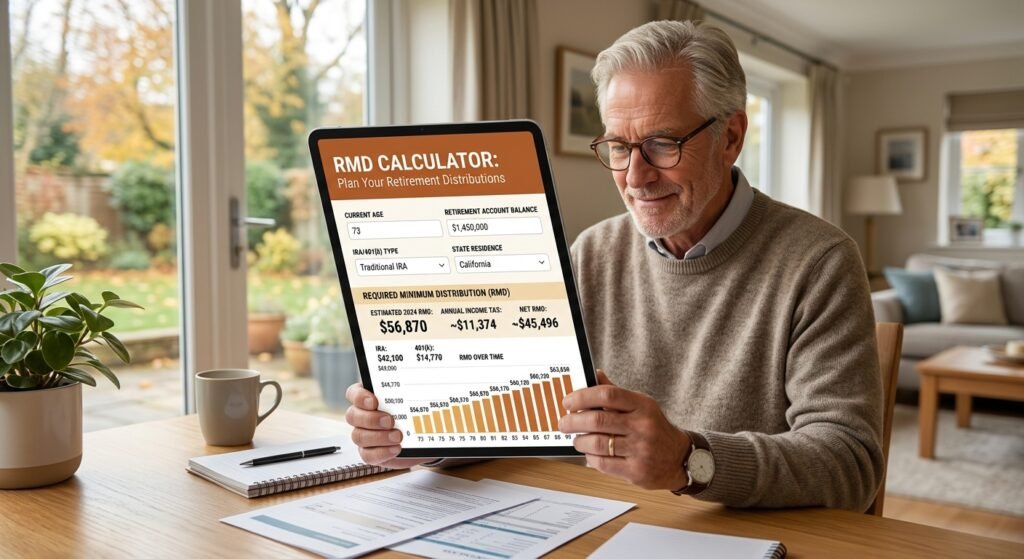
An rmd calculator simplifies complex retirement tax math into a quick, user-friendly process. To get an accurate estimate, the digital tool takes your account balance from the end of the previous year and divides it by a life expectancy factor supplied by official IRS tables. This life expectancy factor reflects a statistical estimate of your remaining years, ensuring that your total account balance gets distributed gradually throughout your lifetime rather than all at once.
Using a modern online rmd calculator allows you to test various scenarios effortlessly. You can input different account balances, adjust expected age milestones, and view projected future distributions within seconds. Rather than sitting down with scratch paper, high-level math formulas, and thick official booklets, you receive an instant estimate that lets you make smart financial choices for your household with total confidence.
Overview of RMD Rules and Standards
| Feature / Metric | Standard Details | Key Highlights |
| Primary Focus Keyword | rmd calculator | Essential tool for calculating mandatory tax withdrawals |
| Starting Age Threshold | Age 73 (moving to 75 in 2033) | Established under updated SECURE Act 2:0 federal guidelines |
| Account Types Included | Traditional IRA, 401(k), 403(b), SEP IRA, SIMPLE IRA | Applies to most tax-deferred retirement savings accounts |
| Calculation Valuation Date | December 31st of the prior year | Account balance on this exact date determines the payout |
| Annual Withdrawal Deadline | December 31st (April 1st for first year) | Strict annual deadline to avoid mandatory IRS penalties |
| Missed Penalty Rate | 25% (reducible to 10% if fixed fast) | Formerly 50%; highlights the importance of accurate math |
When Do You Need to Start Taking Mandatory Withdrawals?
Knowing your exact starting age is critical because tax laws have shifted in recent years. Under older guidelines, retirees had to start taking distributions when they turned seventy and a half. Recent legislation known as the SECURE Act raised this mandatory starting age to seventy-two, and then raised it again to seventy-three. This means if you reach age seventy-three, you must officially begin taking your mandatory payouts from tax-deferred savings accounts.
Your very first mandatory payout gives you a slight grace period. You have until April first of the year following the calendar year in which you turn seventy-three to take your first distribution. However, every subsequent year after that first payout, your deadline remains December thirty-first. Be careful when delaying your first payment until April, as doing so means taking two full payouts in a single calendar year, which might push your household into a higher income tax bracket.
Using an RMD Calculator 2025 for Your Current Planning
If you are planning your upcoming tax year, utilizing an rmd calculator 2025 is the smartest way to organize your upcoming household expenses. Each year requires a fresh calculation because your total account balance changes based on stock market performance, interest earned, and previous withdrawals. Additionally, your life expectancy factor on official distribution charts decreases as you grow older, changing the required payout percentage.
By running an rmd calculator 2025, you can figure out your exact mandatory payout well before the end-of-year deadline arrives. Early calculation gives you ample time to contact your financial institution, request the exact cash transfer, and plan for any taxes owed on that income. Preparing your financial steps early prevents last-minute panics in December when banks and brokerage firms handle heavy end-of-year request volumes.
How to Read an RMD Calculator Table Correctly
To understand where your numbers come from, it helps to examine an official rmd calculator table. The tax authority provides specific life expectancy tables that outline a standard distribution factor for every single age starting at age seventy-two and above. The most common table used by standard retirees is called the Uniform Lifetime Table, designed for single individuals, married owners whose spouses are not more than ten years younger, or individuals whose spouses are not the sole beneficiaries.
To calculate your required payout manually using an rmd calculator table, locate your current age on the official chart to find your corresponding distribution factor. Next, find your total account balance recorded on December thirty-first of the previous year. Divide your balance by your matching distribution factor to reveal your total required payout. A reliable rmd calculator automates this step completely, removing any chance of human calculation error.
Finding Your Exact Numbers: RMD Calculator by Age
Your annual distribution amount changes continuously because your age dictates your life factor. Using an rmd calculator by age demonstrates clearly how mandatory percentages gradually rise as time moves forward. For instance, at age seventy-three, your distribution factor on standard tables starts around 26.5. If your total traditional savings account held $100,000 on December thirty-first, dividing that balance by 26.5 yields an initial distribution requirement of roughly $3,773.
As you celebrate more birthdays, your distribution factor steadily decreases, which means you must withdraw a slightly higher percentage of your remaining account balance each year. By checking an rmd calculator by age, you can model your future cash flows over five, ten, or fifteen years. This projection helps you see how much cash you will receive and how your overall account balance might change across your retirement journey.
Why the AARP RMD Calculator Is a Popular Choice
Many retirees looking for simple financial tools frequently rely on the aarp rmd calculator. This widely used online tool is built with clear visual layouts, intuitive input boxes, and helpful explanations tailored specifically for senior account holders. It helps everyday retirees double-check their yearly mandatory distribution numbers without requiring complex financial expertise or downloading confusing software packages.
While using an aarp rmd calculator offers great convenience and clear insights, it is always a smart habit to compare results using multiple financial tools or consult with a trusted financial planner. Checking multiple calculators confirms your baseline numbers and gives you absolute confidence before making formal withdrawal requests from your investment accounts.
Step-by-Step Instructions to Calculate Your Distribution
Calculating your required annual payout is straightforward when you follow a clear, organized process. By gathering your account details ahead of time, you can complete your calculations smoothly in just a few minutes:
- Gather Year-End Statements: Collect all official year-end bank and brokerage account statements showing your ending balance on December thirty-first of the previous year.
- Identify Eligible Accounts: Separate traditional IRAs, rolled-over 401(k) plans, and SEP IRAs from Roth accounts, which generally do not require distributions during the original owner’s lifetime.
- Determine Your Current Age: Use the exact age you will reach during the current calendar tax year.
- Locate Your Distribution Factor: Find your standard life expectancy number using the standard IRS Uniform Lifetime Table or an automated online rmd calculator.
- Divide Account Balance by Factor: Divide your total year-end balance by your assigned life expectancy factor to reveal your exact required dollar distribution.
- Schedule Your Cash Distribution: Contact your financial institution to arrange your cash distribution before the official deadline arrives.
Common Mistakes to Avoid When Taking Required Distributions
One frequent mistake retirees make is calculating their mandatory distribution based on their current bank account balance rather than the balance from December thirty-first of the previous year. If your portfolio grows or drops in value during the year, your required payment amount remains tied strictly to that previous year-end balance figure. Using today’s balance instead of last year’s balance can result in an incorrect distribution amount.
Another common pitfall involves confusing multiple traditional IRAs. While you must calculate the required distribution for each individual traditional IRA account you own, the government permits you to take the total combined payout amount from just one single IRA or spread it across multiple IRAs as you choose. However, this aggregation rule does not apply to 401(k) accounts; required distributions for separate employer 401(k) plans must be calculated and taken individually from each respective account.
Smart Strategies to Manage Taxes on Your Withdrawals
Because mandatory payouts count as regular taxable income, they can push your annual earnings into a higher tax bracket or increase taxes on your Social Security benefits. One popular strategy to manage this tax impact is making a Qualified Charitable Distribution (QCD). If you are age seventy and a half or older, you can transfer money directly from your traditional IRA to a qualified charity. This direct transfer counts toward satisfying your mandatory distribution without adding taxable income to your annual return.
Another effective strategy involves setting aside money for estimated taxes ahead of time. When requesting your distribution, you can ask your account custodian to automatically withhold federal and state taxes from your payment. Taking this proactive step prevents unexpected tax bills when filing your annual tax return and helps you manage your household cash flow smoothly throughout the year.
Frequently Asked Questions (FAQs)
What happens if I forget to take my mandatory distribution on time?
If you miss your distribution deadline, you may face an IRS penalty tax on the amount not withdrawn. Under current rules, this penalty is twenty-five percent, but it can be reduced to ten percent if you take the missing amount quickly and file a waiver request explaining the honest oversight.
Do I have to take mandatory distributions from a Roth IRA?
No, original owners of Roth IRAs are not required to take mandatory distributions during their lifetime. Because contributions to Roth IRAs are made with after-tax dollars, your savings grow tax-free and can remain in your account for as long as you live.
Can I withdraw more money than the calculated minimum amount?
Yes, you can always withdraw more than your required minimum distribution amount. However, taking extra money increases your taxable income for that year, and extra amounts withdrawn cannot be applied toward future years’ required distributions.
How does an rmd calculator handle multiple retirement accounts?
An rmd calculator computes the required payout for each individual account balance you enter. You can add your traditional IRAs together to take one combined distribution, but 401(k) plan payouts must be calculated and withdrawn from each account separately.
What year-end balance should I use for my calculation?
You must always use your total account balance from December thirty-first of the previous calendar year. For example, your 2025 calculation relies entirely on your verified account balance from December 31, 2024.
Are inherited IRAs subject to the same withdrawal rules?
Inherited IRAs follow special rules depending on when you inherited the account and your relationship to the original owner. Many non-spouse beneficiaries are required to withdraw the entire account balance within ten years, making it wise to consult a financial specialist.
Conclusion
Managing your retirement finances does not have to be overwhelming or complicated. By using a reliable rmd calculator, staying mindful of key age milestones, and keeping track of your official year-end account balances, you can meet all tax requirements with total confidence. Taking a proactive approach ensures you avoid unnecessary penalties, control your tax burden, and protect the wealth you worked hard to build.
Have you checked your withdrawal strategy for this year? Take a moment today to gather your account statements, try out an online rmd calculator, or speak with a qualified tax professional to keep your retirement plan running smoothly!